Internal controls to prevent fraud help business owners protect cash, financial information, and company resources before suspicious activity becomes a serious problem.
Fraud does not always begin with a dramatic event. It can start with an unauthorized payment, a duplicate invoice, an altered payroll record, or a transaction that no one reviews. When these activities remain undetected, the resulting losses can affect cash flow, profitability, employee trust, and the reputation of the business.
Many entrepreneurs believe fraud will not happen because they trust their employees or work with long-standing vendors. Trust is valuable, but it should be supported by clear processes. Strong internal controls create accountability without assuming that every mistake is intentional.
By establishing approval requirements, separating financial responsibilities, securing payment methods, and reviewing transactions consistently, business owners can reduce both fraud risk and costly accounting errors.
Internal controls are the policies, procedures, and review processes a company uses to protect its assets and maintain reliable financial records.
These controls determine:
Effective controls make financial activity easier to verify. They also create a clear record showing who initiated, approved, recorded, and reviewed a transaction.
Internal controls cannot guarantee that fraud will never occur. However, they can make fraud more difficult to commit, increase the likelihood of early detection, and limit the potential damage.
Internal controls to prevent fraud are especially important for growing businesses and companies managing multiple entities, locations, employees, or bank accounts.
As a company expands, more people may become involved in purchasing, payroll, reimbursements, deposits, and vendor management. Without clearly defined responsibilities, it becomes easier for unauthorized transactions or accounting mistakes to go unnoticed.
The Association of Certified Fraud Examiners identifies surprise audits, financial statement audits, reporting hotlines, and proactive data analysis among the controls associated with lower fraud losses and faster detection.
The goal is not to create unnecessary bureaucracy. It is to introduce practical checks and balances that match the size, structure, and financial risks of the business.
No single employee should control every stage of a financial transaction.
Whenever possible, divide responsibilities among different people. For example:
This separation makes it more difficult for one person to create, approve, and conceal an unauthorized transaction.
Small businesses may not have enough employees to separate every responsibility completely. In that situation, the owner or an external accounting professional can perform an independent review.
For example, the owner might review monthly bank statements, canceled checks, vendor changes, payroll reports, and reconciliation summaries. Even a simple secondary review can create meaningful accountability.
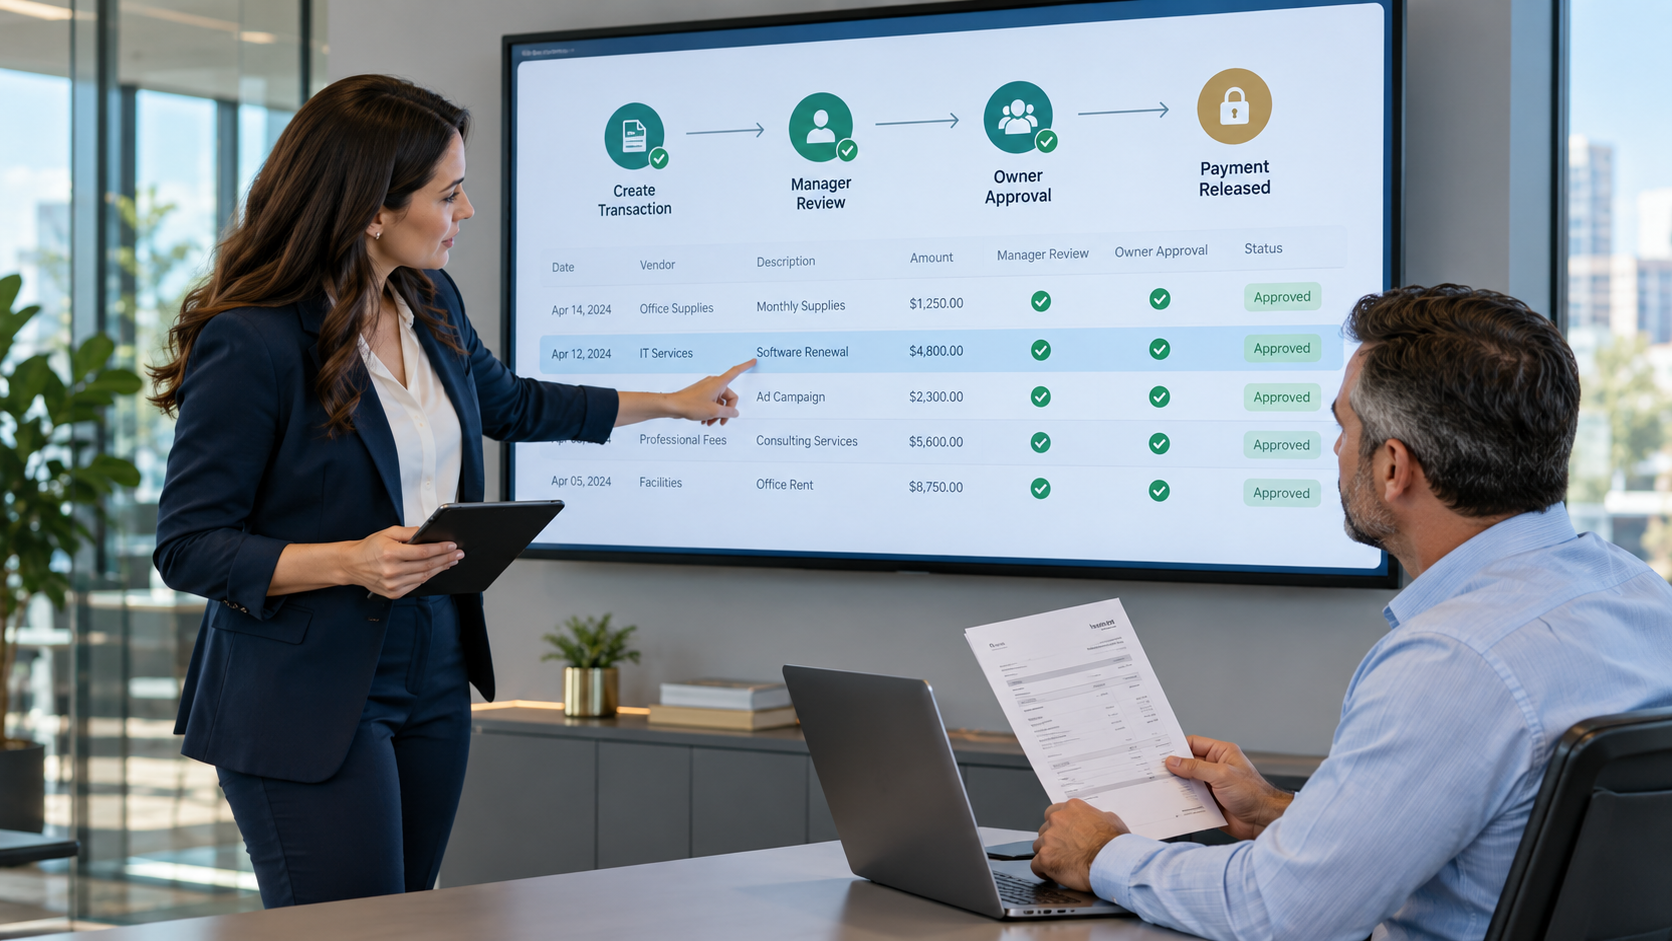
Every business should define which transactions require approval and who has the authority to approve them.
Approval policies may cover:
Internal controls to prevent fraud work best when approval requirements are documented and applied consistently.
A verbal approval may be difficult to verify later. Whenever possible, approvals should be documented through the accounting system, email, expense platform, or another secure workflow.
The approval threshold should match the size of the business. A company does not need executive approval for every small purchase, but high-value or unusual transactions should receive additional scrutiny.
Bank and credit card reconciliations compare the company’s accounting records with the transactions reported by its financial institutions.
Completing reconciliations every month can help identify:
The person completing the reconciliation should not be the only person with authority to initiate payments or modify transactions.
Management should also review the completed reconciliation, investigate unusual items, and document any necessary corrections. A reconciliation that is completed but never reviewed may not provide sufficient protection.
Businesses with a high volume of transactions may benefit from weekly reviews or automated transaction alerts in addition to monthly reconciliation.
Bank accounts, business credit cards, payment platforms, and accounting systems should only be accessible to employees who need them.
Strong access controls include:
Avoid sharing usernames and passwords. Shared credentials make it difficult to identify who completed a transaction and increase the risk of unauthorized access.
Dual approval is particularly useful for wire transfers, ACH payments, payroll changes, and large vendor payments. One person can prepare the transaction while another verifies the supporting documentation and authorizes the release.
These internal controls to prevent fraud also protect the company from external threats involving stolen credentials or fraudulent payment instructions.
Vendor fraud can occur when a false vendor is created, an invoice is duplicated, or legitimate payment information is replaced with fraudulent banking instructions.
Before approving a new vendor, verify:
Requests to change vendor banking information should receive additional scrutiny. Do not rely exclusively on the email requesting the change. Contact the vendor using a previously verified telephone number or contact person.
Invoices should be matched with purchase orders, contracts, delivery confirmations, or other evidence that the goods or services were actually received.
Businesses should also review vendor lists for duplicate names, matching addresses, unusual payment patterns, inactive vendors, and payments that fall just below approval thresholds.
Financial reports can reveal patterns that individual transactions may not show.
Business owners should review:
Unexpected changes should lead to questions. A sudden increase in payroll, frequent refunds, unusual vendor payments, or declining margins may have a legitimate explanation, but the business should investigate the cause.
Internal controls to prevent fraud should include automated alerts for high-value transactions, payments to new recipients, unusual login activity, or changes to financial information.
The accounting system should also maintain an audit trail showing who created or modified transactions. Audit logs are only valuable when someone reviews them.
Professional accounting and controller services can help businesses organize their records, review financial activity, and establish more consistent reporting processes.
Employees are often the first people to notice suspicious behavior, unusual requests, or weaknesses in a financial process. Businesses should provide a safe and clearly communicated method for reporting concerns.
Depending on the size of the company, this may include:
Every report should be handled carefully and consistently. Business owners should avoid making immediate accusations before the facts have been reviewed.
Periodic audits and surprise reviews can also strengthen the control environment. The purpose is not only to discover fraud but also to confirm that existing procedures are being followed.
An audit may include reviewing expense reports, tracing payments to supporting documentation, verifying vendor information, examining user access, and testing approval procedures.
For additional general fraud-prevention guidance, business owners can also review our article on how to protect your business from fraud.
Internal controls to prevent fraud should be designed around the actual operations of the business. A process that is unnecessarily complicated may eventually be ignored, while a process that is too informal may not provide adequate protection.
Start by identifying the areas where money or sensitive information changes hands:
For each area, document who initiates transactions, who approves them, who records them, and who reviews the results.
Next, identify situations in which one person has too much control or where no independent review exists. Introduce practical safeguards such as approval limits, monthly reviews, dual authorization, automated alerts, and restricted system access.
Internal controls should be reviewed whenever the company hires employees, changes software, opens another location, adds an entity, or modifies its banking relationships. Controls that worked for a small operation may no longer be sufficient as the business grows.
Internal controls are most effective when owners know what unusual activity may look like. Potential warning signs include:
A warning sign does not automatically prove that fraud has occurred. It indicates that the transaction or behavior deserves closer examination.
If fraud is suspected, the business should preserve relevant records and consult appropriate accounting, legal, human resources, or fraud-investigation professionals before confronting anyone or taking formal action.
Internal controls to prevent fraud are not based on distrust. They are a responsible part of managing a company’s money, information, and long-term stability.
Separating financial duties, documenting approvals, reconciling accounts, restricting system access, verifying vendors, monitoring reports, and creating a confidential reporting process can make fraudulent activity more difficult to commit and easier to detect.
Strong controls can also improve financial accuracy, reduce errors, clarify employee responsibilities, and give business owners greater confidence in their reports.
If you manage multiple entities, locations, or financial accounts and need help strengthening your accounting processes, schedule a consultation with NeatBooks. Our team can help you establish organized financial workflows, reliable reporting, and practical internal controls that support a safer and more transparent business.
Privacy Policy | Terms and Conditions | Powered by Purity
At NeatBooks, we know you want to focus on growing your business without the stress of messy books, missed deadlines, or worrying if you’re leaving money on the table. The problem is, financial complexity and unreliable support from previous accountants can leave you feeling stuck, overwhelmed, and vulnerable to costly mistakes.
It doesn’t have to be this way! Every entrepreneur deserves a financial partner who simplifies the chaos, provides proactive guidance, and empowers them to make confident decisions.
With over 300 businesses transformed and a team that speaks your language (no jargon, just straight talk), NeatBooks combines expert financial strategies with a personal touch. We’re here to turn complexity into clarity and help you ProsperNeatly™.
Here’s how we do it:
Step 1: Schedule a Discovery Call - Let’s understand if we are a good fit, first. Then, we’ll move
into an assessment of where you are and what actions we need to take together to help you gain
clarity and financial organization.
Step 2: Strategize & Optimize - Together, we build a plan customized for your business and
your goals, and we execute.
Step 3: ProsperNeatly™ - You gain the confidence that comes with having a reliable, competent
partner managing the financial side of your business.
Let’s get started by scheduling a Discovery Call today. In 15 minutes, you’ll know how we can impact your business.
In the meantime, we invite you to download any of our free resources that have been built to support entrepreneurs in the food service, construction, and real estate development and investment spaces